How Much Can You Earn Before Paying Tax in the UK?

Last Updated: 2 November 2026
For most people in the UK, you can earn up to £12,570 a year before paying Income Tax. This is because the standard Personal Allowance for the 2026/27 tax year is £12,570.
For employees receiving the standard allowance, this works out at around £1,048 per month or £242 per week for PAYE purposes.
However, the exact amount you can receive before tax becomes more complicated if you have more than one job, earn money from a side hustle, work for yourself, receive rental or investment income, or earn more than £100,000.
The tax year runs from 6 April 2026 to 5 April 2027, and different Income Tax bands apply in Scotland.
The Standard Tax-Free Threshold Explained
The Personal Allowance is the amount of income you can normally receive before Income Tax starts to apply.
For 2026/27, the standard Personal Allowance remains £12,570.
For someone living in England, Wales or Northern Ireland and receiving the full allowance, the main Income Tax bands are:
| Annual Income | Income Tax Rate |
| Up To £12,570 | 0% |
| £12,571 To £50,270 | 20% |
| £50,271 To £125,140 | 40% |
| Over £125,140 | 45% |
These are marginal tax rates. This means that moving into a higher tax band does not cause all of your earnings to be taxed at the higher percentage.
Only the part of your income falling within that band is taxed at that rate.
For example, if you earn £30,000 and receive the full Personal Allowance, the first £12,570 is normally tax-free.
The remaining £17,430 falls within the basic-rate band and is generally taxed at 20%.
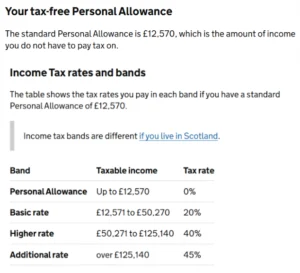
GOV.UK confirms the £12,570 Personal Allowance and current Income Tax bands.
For many employees receiving the full allowance, the standard tax code is 1257L.
However, a different code can apply when you have another job, taxable benefits, unpaid tax or other adjustments, so it is worth checking whether your tax code is correct if the amount being deducted from your wages looks unusual.
The £12,570 allowance also does not remain available in full to every high earner.
Once your adjusted net income exceeds £100,000, your Personal Allowance falls by £1 for every £2 above the £100,000 threshold. It disappears completely once income reaches £125,140.
For example:
- Adjusted Net Income: £110,000
- Income Above £100,000: £10,000
- Personal Allowance Lost: £5,000
- Remaining Personal Allowance: £7,570
This withdrawal creates the well-known £100k tax trap, where earnings between £100,000 and £125,140 can face an unusually high effective marginal Income Tax rate.
How Much Can You Earn Before Paying Tax Per Month And Per Week?
The £12,570 annual Personal Allowance can also be viewed in weekly and monthly terms for PAYE.
| Pay Period | Standard PAYE Threshold |
| Weekly | £242 |
| Monthly | £1,048 |
| Annual | £12,570 |
HMRC confirms these standard employee Personal Allowance figures for the 2026/27 tax year.
This does not necessarily mean you will pay no tax whenever one individual payslip falls below £1,048.
PAYE can operate cumulatively, meaning your employer may consider how much you have earned and how much allowance you have used during the tax year.
Bonuses, overtime and irregular hours can also affect deductions in individual pay periods.
For example, someone earning £14 an hour may be above the annual Personal Allowance even if their weekly hours vary.
Looking at a £14 per hour monthly salary after tax shows how annual earnings, rather than simply the hourly rate, determine the Income Tax due.
How Much Can You Earn Self-Employed Before Paying Tax?
Self-employed people are normally taxed on their taxable profits, rather than simply the total amount customers pay them.
If you have no other taxable income and qualify for the full Personal Allowance, you can generally have taxable profits of up to £12,570 before Income Tax becomes payable.
However, self-employed workers also need to understand the separate £1,000 Trading Allowance.
These two allowances should not be confused.
The Personal Allowance is the main tax-free income allowance available to most individuals.
The Trading Allowance is a separate allowance of up to £1,000 for qualifying trading income.
HMRC says that if your annual gross trading income is £1,000 or less, you may not normally need to tell HMRC about it, although exceptions apply.
If gross trading income exceeds £1,000, you generally need to register for Self Assessment.
For example, imagine you earn £4,000 from freelance work and decide to use the Trading Allowance.
- Gross Trading Income: £4,000
- Trading Allowance: £1,000
- Income Remaining: £3,000
Whether Income Tax is actually due on that £3,000 depends on your other taxable income and how much of your Personal Allowance is still available.
You can generally choose between deducting the Trading Allowance or claiming allowable business expenses.
You cannot normally claim the £1,000 Trading Allowance and deduct actual expenses against the same trading income.
This distinction is particularly important for people with side businesses because earning more than £1,000 does not automatically mean you owe Income Tax. It can instead mean that you have a reporting obligation.
What If You Have A Job, Side Hustle Or Second Job?
Having two sources of income does not normally mean you receive two Personal Allowances.
Your £12,570 Personal Allowance applies across your taxable income.
Suppose you earn:
| Income Source | Annual Amount |
| Main Employment | £30,000 |
| Freelance Income | £5,000 |
| Combined Income | £35,000 |
You do not receive £12,570 tax-free from your employment and another £12,570 against your freelance income.
Instead, your income is considered together when determining your overall Income Tax liability.
The same issue arises if you have two employed jobs.
For example:
- Main Job: £28,000
- Second Job: £6,000
- Total Employment Income: £34,000
Your Personal Allowance may be allocated mainly to your primary employment.
The second job could therefore have tax deducted from the first pound even though you still receive the benefit of your Personal Allowance elsewhere.
Your tax codes are particularly important when you have more than one employment because an incorrect allocation could result in either too much or too little tax being deducted.
Changing employers can also affect PAYE calculations.
Understanding the difference between a P60 and P45 matters because your P45 gives a new employer details about your previous earnings and tax deductions during the current tax year.
How Much Can You Earn Before Paying National Insurance?
Income Tax and National Insurance are two separate deductions, even though both may appear on the same payslip.
For most Category A employees during 2026/27, employee National Insurance starts once earnings exceed the Primary Threshold of £242 per week or £1,048 per month.
The standard rates are:
| Weekly Earnings | Employee National Insurance |
| £129 To £242 | 0% |
| £242.01 To £967 | 8% |
| Above £967 | 2% |
HMRC confirms that Category A employees pay 8% on earnings between the Primary Threshold and Upper Earnings Limit, followed by 2% above the upper limit.
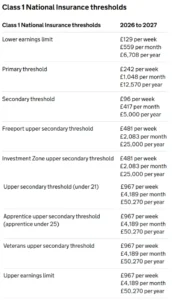
HMRC confirms the weekly, monthly and annual employee National Insurance thresholds for 2026/27.
National Insurance can therefore begin at approximately the same annual earnings level as Income Tax for someone receiving the standard Personal Allowance, but the two systems remain separate.
Different National Insurance rules apply to some categories of employees and to self-employed people.
What Income Counts Towards Taxable Income?
The £12,570 Personal Allowance is not only relevant to your salary.
A range of income can potentially be taxable, including:
- Employment Income: Wages, salaries, bonuses and certain employment benefits
- Self-Employment Profits: Profits made from freelance work, sole trading or other business activity
- Pension Income: Most workplace, private and State Pension income
- Rental Income: Income from property that is not covered by a relevant allowance or relief
- Savings Interest: Interest above any applicable tax-free savings allowance
- Dividend Income: Dividends above the available Dividend Allowance
- Trust Income: Certain payments received from trusts
- Taxable Benefits: Some State Benefits can be subject to Income Tax
HMRC also provides separate allowances for certain types of income. These include a Trading Allowance of up to £1,000 and a Property Allowance of up to £1,000 where the relevant conditions are met.
Some income is completely tax-free. For example, qualifying income held within an ISA is not normally subject to Income Tax.
Capital gains are also different from ordinary income. Selling an asset for a profit can potentially create a Capital Gains Tax liability rather than an Income Tax liability.
This is why asking how much you can “earn” before tax does not always have one answer. The tax treatment depends partly on where the money comes from.
Why Have You Paid Tax If You Earn Less Than £12,570?
Someone earning less than £12,570 over the full tax year would not normally owe Income Tax where the full Personal Allowance applies, but tax can still be deducted temporarily.
Common reasons include:
- Emergency Tax Code: Your employer may not yet have enough information to calculate PAYE correctly
- Incorrect Tax Code: HMRC’s records may not reflect your current circumstances
- Multiple Jobs: Your Personal Allowance may have been allocated to another employment
- Previous Earnings: Income received earlier in the tax year can affect cumulative PAYE calculations
- Taxable Benefits: Company benefits or other taxable income can reduce the allowance available through payroll
- Previous Tax Owed: HMRC can adjust a tax code to collect an earlier underpayment
HMRC lists 1257L W1, 1257L M1 and 1257L X as emergency tax codes for 2026/27.
If too much tax has been deducted, an adjustment may sometimes be made through payroll during the same tax year.
After the tax year ends, HMRC can also review PAYE records and issue a P800 where its calculations show that someone has paid too much or too little Income Tax.
The timing of when a P800 may arrive depends on HMRC completing its reconciliation of the relevant tax year.
Income Tax In Scotland
People living in Scotland have different Income Tax bands for earnings including wages and pensions.
The standard Personal Allowance remains £12,570 for someone entitled to receive it in full, but Scottish Income Tax uses additional tax bands.
For 2026/27:
| Income | Scottish Income Tax Rate |
| Up To £12,570 | 0% |
| £12,571 To £16,537 | 19% |
| £16,538 To £29,526 | 20% |
| £29,527 To £43,662 | 21% |
| £43,663 To £75,000 | 42% |
| £75,001 To £125,140 | 45% |
| Over £125,140 | 48% |
These rates apply to Scottish taxable earnings such as wages and pension income. Savings interest and dividends continue to follow UK-wide tax rules.
The Personal Allowance taper for income above £100,000 also applies to Scottish taxpayers.
Examples Of How Much Tax You Could Pay
The following simple examples show how the Personal Allowance affects Income Tax for someone living in England, Wales or Northern Ireland.
They assume the person receives the full £12,570 Personal Allowance and has no other taxable income or adjustments.
| Annual Income | Income Above Personal Allowance | Approximate Income Tax |
| £10,000 | £0 | £0 |
| £12,570 | £0 | £0 |
| £20,000 | £7,430 | £1,486 |
| £30,000 | £17,430 | £3,486 |
| £40,000 | £27,430 | £5,486 |
| £50,000 | £37,430 | £7,486 |
For example, at £30,000:
£30,000 − £12,570 = £17,430 taxable income
£17,430 × 20% = £3,486 Income Tax
This calculation only shows Income Tax.
Your actual take-home pay may also be reduced by National Insurance, pension contributions, student loan repayments, workplace benefits or other deductions.
It also demonstrates an important feature of the UK tax system. You do not pay tax on your entire salary simply because your income exceeds £12,570.
Only the income above the available Personal Allowance becomes taxable.
When Do You Need To Register For Self Assessment?
Employees whose entire income is taxed correctly through PAYE will not usually need to submit a Self Assessment return simply because they have a job.
You may need to complete one when you have income that has not been fully taxed elsewhere.
HMRC says you must generally send a tax return if you were self-employed as a sole trader and earned more than £1,000 before deducting expenses or tax reliefs during the relevant tax year.
Other circumstances that can require Self Assessment include receiving certain amounts of:
- Rental Income
- Savings Interest
- Dividend Income
- Foreign Income
- Tips And Commission
- Capital Gains
- Partnership Income
If you need to register for Self Assessment for the first time, you normally need to tell HMRC by 5 October following the end of the relevant tax year.
Importantly, the requirement to submit a tax return is not the same as actually owing Income Tax.
Someone can have more than £1,000 of gross self-employed income and therefore need to report it while ultimately having little or no Income Tax to pay because of expenses, the Trading Allowance or unused Personal Allowance.
Conclusion
For most people in the UK, £12,570 is the amount you can earn before paying Income Tax if you receive the full standard Personal Allowance.
For employees, HMRC’s standard PAYE figures equate to approximately £242 per week or £1,048 per month.
However, £12,570 should not be treated as a universal answer for every taxpayer.
People earning more than £100,000 can gradually lose their Personal Allowance.
Someone with a second job does not receive another £12,570 allowance, while self-employed people need to distinguish between the Personal Allowance and the separate £1,000 Trading Allowance.
National Insurance also has its own rules and thresholds, and Scottish taxpayers face different Income Tax bands.
The most accurate way to determine when you will start paying tax is to consider all your taxable income, the allowances available to you and the tax code being used against your earnings.
FAQs
How Much Can I Earn Before Paying Tax?
Most people can earn up to £12,570 a year before paying Income Tax if they qualify for the full standard Personal Allowance.
How Much Can I Earn A Month Before Paying Tax?
The standard PAYE Personal Allowance threshold for 2026/27 is approximately £1,048 per month.
How Much Can I Earn A Week Before Paying Tax?
The standard weekly PAYE threshold is approximately £242 for an employee receiving the full Personal Allowance.
Can I Earn £1,000 From A Side Hustle Tax-Free?
The Trading Allowance can cover up to £1,000 of qualifying gross trading income.
If your gross trading income exceeds £1,000, you generally need to tell HMRC, although this does not automatically mean Income Tax will be due.
Do I Pay Tax On A Second Job?
Possibly. You normally have one Personal Allowance across your income rather than a separate £12,570 allowance for every job.
Can I Earn More Than £12,570 Without Paying Income Tax?
Yes, in some circumstances. Additional allowances and tax reliefs can mean some income above £12,570 remains tax-free, depending on the source of the income and your circumstances.
Why Am I Paying Tax If I Earn Less Than £12,570?
An emergency tax code, incorrect tax code, multiple jobs or earlier earnings can result in PAYE deductions even when your eventual annual income is below £12,570.
What is your reaction?