How To Pay Less Tax On Your Pension In The UK?

Last Updated: 26 October 2026
Pensions are one of the most tax-efficient ways to save for retirement in the UK, but that does not mean every pension withdrawal is tax-free.
Once you begin accessing your pension, the amount you withdraw, the way you take it and your other income can determine how much Income Tax you pay.
For most people, the objective is therefore not to find a way to make all pension income tax-free.
Instead, it is to use the available tax-free allowances and structure withdrawals carefully so that unnecessary higher-rate tax is avoided.
For the 2026/27 tax year, the standard Personal Allowance remains £12,570.
Most people can also normally take up to 25% of their pension tax-free, subject to the standard £268,275 Lump Sum Allowance.
The most tax-efficient approach will depend on the size of your pension, State Pension entitlement, other income, savings, ISA holdings and whether you intend to continue paying into pensions.
Understanding How Your Pension Withdrawals Are Taxed
Money held inside a registered pension generally grows without Income Tax or Capital Gains Tax being charged in the same way as ordinary investments outside a pension.
The tax position changes when money is withdrawn.
Normally, you can take part of a pension tax-free while the remaining taxable pension income is added to your other taxable income for the tax year.
For 2026/27, the standard Personal Allowance is £12,570. This means someone whose total taxable income does not exceed their available Personal Allowance would normally have no Income Tax to pay.
For pension income in England, Wales and Northern Ireland, the main 2026/27 rates are:
| Income Band | Income Tax Rate |
| Personal Allowance | 0% Up To £12,570 |
| Basic Rate | 20% |
| Higher Rate | 40% |
| Additional Rate | 45% |
The standard basic-rate band covers £37,700 of taxable income after allowances.
The Personal Allowance also begins to reduce when adjusted net income exceeds £100,000, falling by £1 for every £2 above that level.
Scottish residents have different Income Tax bands for pension income.
In 2026/27, Scottish rates range from a 19% Starter Rate to a 48% Top Rate, so a withdrawal strategy suitable for someone in England may produce a different tax result for someone living in Scotland.
Pension Tax Rates For 2026/27
Pension providers normally deduct Income Tax from taxable pension payments through PAYE.
The tax payable therefore depends on your combined taxable income rather than simply the size of one pension.
For example, someone receiving:
- £12,000 From A Workplace Pension
- £8,000 From Another Private Pension
- £12,000 Of Other Taxable Income
could have £32,000 of taxable income before considering any tax-free pension lump sums.
This is why looking at each pension separately can give a misleading picture.
If several pensions are being paid through PAYE, it is also important to check which pension is using your Personal Allowance.
An unexpected BR, D0, 0T or K code can materially affect the amount deducted.
You can check whether your tax code is correct if the deductions from a pension do not match your expected tax position.
How Much Pension Income Is Tax-Free?
There are two separate tax-free concepts that are often confused.
The first is your Personal Allowance, which normally allows £12,570 of taxable income before Income Tax starts.
The second is the tax-free element available when accessing eligible pension savings.
You can normally take up to 25% of your pension tax-free, subject to your remaining Lump Sum Allowance.
The standard Lump Sum Allowance for 2026/27 is £268,275.
That does not mean everyone can automatically receive £268,275. It is a maximum standard allowance.
Someone would generally need pension benefits of at least £1,073,100 to reach that amount through the usual 25% calculation.
Some people with protected pension rights may be entitled to a larger tax-free amount.
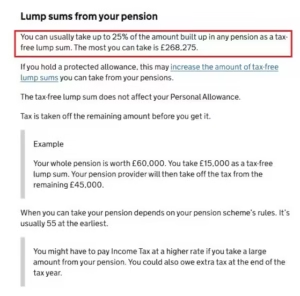
GOV.UK confirms that up to 25% of pension savings can normally be taken tax-free, subject to the £268,275 standard Lump Sum Allowance.
Ways To Take Money From Your Pension More Tax-Efficiently
There is no single withdrawal method that produces the lowest tax for every retiree.
The main advantage of pension flexibility is that people with defined contribution pensions may be able to control when taxable income is created.
A person who needs £30,000 to spend during a year does not necessarily need to create £30,000 of taxable pension income.
They might instead use a combination of tax-free pension cash, taxable drawdown and tax-free ISA withdrawals.
25% Tax-Free Pension Lump Sum
Most eligible pension savers can normally take up to 25% of their pension tax-free.
For example, from a £200,000 pension pot, the usual maximum tax-free amount could be:
£200,000 × 25% = £50,000
The remaining £150,000 is not automatically taxed immediately. It can normally remain invested and be withdrawn later, with taxable withdrawals taxed when they are taken.
Taking the entire £50,000 tax-free amount immediately is not always necessary.
Some pension arrangements allow tax-free cash to be taken gradually as portions of the pension are crystallised.
This can allow retirees to coordinate pension withdrawals with their annual spending requirements.
However, the appropriate approach depends on the pension scheme and the individual’s wider finances.
Flexi-Access Drawdown And UFPLS
Two commonly used flexible withdrawal methods are flexi-access drawdown and Uncrystallised Funds Pension Lump Sums, usually called UFPLS.
With UFPLS, each qualifying withdrawal is normally divided so that:
- 25% Is Tax-Free
- 75% Is Taxable
HMRC’s pension guidance describes this treatment for UFPLS payments.
Suppose someone withdraws £20,000 using UFPLS.
Normally:
| Portion | Amount |
| Tax-Free 25% | £5,000 |
| Taxable 75% | £15,000 |
| Total Withdrawal | £20,000 |
Flexi-access drawdown works differently.
A person may normally take pension commencement tax-free cash when funds are moved into drawdown.
Future withdrawals from the drawdown fund are then taxable pension income.
That distinction matters when planning withdrawals because two people receiving the same amount of cash could have different taxable income depending on how the pension payment was structured.
Spreading Withdrawals Across Tax Years
One of the most effective ways of reducing pension tax can be avoiding unnecessarily large taxable withdrawals in one tax year.
Consider an illustrative example of someone with no other taxable income who accesses £100,000 through UFPLS.
If the full £100,000 were withdrawn in one tax year:
- £25,000 could normally be tax-free
- £75,000 would normally be taxable
- Part of the taxable amount would fall into the 40% Income Tax band
Using 2026/27 England, Wales and Northern Ireland rates, the illustrative Income Tax on the taxable portion would be around £17,432, assuming the full standard Personal Allowance is available.
Now compare that with taking five separate £20,000 UFPLS withdrawals over five tax years.
Using today’s 2026/27 allowances and rates purely for illustration, each £20,000 payment would consist of £5,000 tax-free and £15,000 taxable.
With a £12,570 Personal Allowance, only £2,430 would be taxable at 20%, producing approximately £486 of Income Tax each year.
If the same allowances and rates applied throughout all five years, total tax would be approximately £2,430.
| Withdrawal Strategy | Illustrative Tax Using 2026/27 Rates |
| £100,000 UFPLS In One Year | About £17,432 |
| £20,000 UFPLS Each Year For Five Years | About £2,430 |
| Illustrative Difference | About £15,002 |
This example assumes no State Pension, salary, rental income or other taxable income and assumes current allowances continue. Future tax rates can change.
It demonstrates why timing can matter just as much as the amount withdrawn.
How To Reduce Tax On Pension Withdrawals?
The key to reducing pension tax legally is usually to manage taxable income across different sources.
Stay Within Lower Income Tax Bands
Before taking a large pension payment, calculate your expected total taxable income for the entire tax year.
This could include:
- State Pension
- Workplace Pension Income
- Private Pension Income
- Employment Income
- Self-Employment Profits
- Rental Income
- Taxable Savings Income
A withdrawal that appears relatively small on its own can push part of your income into a higher tax bracket when added to your other income.
For someone close to the higher-rate threshold, delaying part of a pension withdrawal until after 6 April could sometimes prevent that amount being taxed at a higher marginal rate.
Combine Pension Withdrawals With ISA Income
ISA withdrawals can be particularly useful when managing retirement income because income and gains within an ISA are generally tax-free.
Suppose someone requires £35,000 for annual spending.
Instead of taking the full £35,000 as taxable pension income, they might be able to meet part of that requirement from an ISA.
For example:
- £20,000 From Pension Income
- £15,000 From An ISA
The ISA withdrawal itself would not normally be added to taxable income.
This can help keep pension income within a lower tax band, although drawing heavily from an ISA also reduces the amount remaining in that tax-efficient wrapper.
People holding cash outside an ISA should also consider how savings interest interacts with their tax position.
Interest held inside ISAs remains tax-free, while ordinary savings interest may become taxable once relevant allowances are exceeded, as explained in this overview of whether HMRC needs to be notified about savings interest.
Avoid the £100,000 Personal Allowance Tax Trap
Large pension withdrawals require particular care when total adjusted net income approaches £100,000.
For 2026/27, the Personal Allowance is reduced by £1 for every £2 of adjusted net income above £100,000.
By £125,140, the standard Personal Allowance has been completely removed.
For example, someone with £80,000 of other taxable income who takes a further £30,000 taxable pension withdrawal could move into the Personal Allowance taper.
Taking part of the withdrawal in another tax year may produce a better tax result, depending on expected future income.
This is an area where professional tax or regulated financial advice can be particularly valuable because pension withdrawals generally cannot simply be reversed after the money has been taken.
How Does the State Pension Affect Your Tax?
The State Pension is taxable income.
However, the Department for Work and Pensions normally pays it without deducting Income Tax first.
HMRC then considers State Pension alongside other taxable income and may collect tax through PAYE on a workplace pension, private pension or employment income.
Is The State Pension Taxable?
Yes. For 2026/27, the full new State Pension is £241.30 per week.
Over 52 weeks that is approximately:
£241.30 × 52 = £12,547.60
Compare this with the standard Personal Allowance of £12,570.
That leaves only about:
£22.40
of the standard Personal Allowance before considering any other taxable income.
This is significant for retirees receiving the full new State Pension.
Even a relatively small private or workplace pension could therefore result in an Income Tax liability.
The exact taxable State Pension used by HMRC may differ slightly from simply multiplying the weekly rate by 52 because HMRC calculates entitlement over the tax year according to its State Pension taxation rules.
State Pension And The Personal Allowance
The State Pension does not have a separate tax-free pension allowance.
Instead, it uses part of the same Personal Allowance as other taxable income.
Suppose someone receives:
- £12,547.60 State Pension
- £8,000 Workplace Pension
Their approximate total taxable income would be £20,547.60.
Assuming the full £12,570 Personal Allowance is available, approximately £7,977.60 would remain taxable.
For someone subject to a 20% rate, that would produce approximately £1,595.52 of Income Tax before considering any other adjustments.
Because tax is not normally deducted directly from State Pension payments, HMRC may adjust the PAYE code attached to another pension.
This is one reason pensioners can encounter K codes or other unexpected tax-code changes.
Emergency Tax On Pension Withdrawals
One of the most frustrating pension-tax problems occurs when someone makes their first flexible pension withdrawal and considerably more tax is deducted than expected.
Pension providers normally use PAYE when making taxable pension payments.
If the provider does not yet hold an appropriate tax code, an emergency Week 1 or Month 1 basis may be used. HMRC guidance confirms that this can happen with pension flexibility payments.
Under this approach, the PAYE calculation can effectively treat a large one-off payment as though similar income could continue throughout the year.
The initial deduction can therefore be much higher than the person’s eventual annual tax liability.
The issue is sufficiently common that HMRC processed 10,200 P55 forms, 2,001 P53Z forms and 411 P50Z forms between 1 April and 30 June 2026, refunding more than £50 million across pension-flexibility repayment claims.
People approaching their first flexible pension payment may find it useful to understand how an emergency tax code can affect an initial pension withdrawal before choosing how much to take.
Why Emergency Tax Is Applied?
Emergency taxation usually arises because the pension provider does not have enough PAYE information to calculate the individual’s annual position accurately.
A code operating on a Week 1 or Month 1 basis looks only at the allowance and tax bands available for that pay period rather than calculating PAYE cumulatively using the full tax year.
This does not necessarily mean the tax has been permanently lost.
If too much Income Tax has been deducted, it may be reclaimable.
How To Claim Back Overpaid Pension Tax?
HMRC provides different refund routes depending on how the pension was accessed.
Common forms include:
| Form | Typical Situation |
| P55 | Part of a pension was flexibly accessed |
| P53Z | The whole pension was flexibly accessed and other taxable income continues |
| P50Z | The whole pension was flexibly accessed and there is no continuing income other than State Pension |
| P53 | Certain small pension lump-sum repayments |
HMRC now provides an online service to determine the appropriate pension-tax refund route.
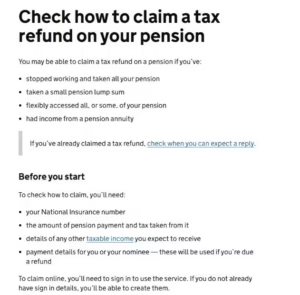
GOV.UK confirms when pension savers may be able to claim back overpaid tax after accessing their pension.
If the tax year has already ended or another repayment issue is involved, it can also be worth checking whether HMRC owes you a tax rebate rather than assuming an excessive deduction will automatically be corrected immediately.
Small Pension Pots And The Money Purchase Annual Allowance
Different rules can apply to relatively small pension pots.
£10,000 Small Pension Pot Rules
A pension worth £10,000 or less may usually qualify to be taken as a small-pot lump sum.
If the pension has not previously been accessed, normally 25% is tax-free, with the remainder taxable.
HMRC rules generally allow:
- Up To Three Small Personal Pension Pots Of £10,000 Or Less
- Unlimited Qualifying Small Workplace Pension Pots Of £10,000 Or Less
There is also a separate trivial commutation rule.
Where all relevant private pension rights are £30,000 or less, it may be possible to take certain pensions, commonly defined benefit pensions, as a trivial commutation lump sum subject to the qualifying conditions.
These rules should not be confused with a general right to withdraw any pension below £30,000 tax-free.
The taxable part of a small-pot or trivial commutation payment can still be subject to Income Tax.
£10,000 Money Purchase Annual Allowance
People who intend to continue contributing to pensions after making withdrawals should pay particular attention to the Money Purchase Annual Allowance, or MPAA.
For 2026/27, the MPAA is £10,000.
It can be triggered when someone flexibly accesses taxable benefits from a defined contribution pension.
Once triggered, it can significantly restrict the amount that can subsequently be contributed to money purchase pensions without potentially creating an annual allowance tax charge.
The normal pension Annual Allowance for 2026/27 is £60,000, subject to the relevant rules and possible tapering for high earners.
That creates an important distinction:
| Allowance | 2026/27 Amount |
| Standard Annual Allowance | £60,000 |
| Money Purchase Annual Allowance | £10,000 |
Taking only an eligible pension commencement lump sum without taxable flexible income does not necessarily trigger the MPAA, whereas certain flexible taxable withdrawals can.
Anyone planning to withdraw pension money while still making significant pension contributions should check the MPAA implications before taking the payment.
Tax On Inherited Pensions And The 2027 Inheritance Tax Changes
The taxation of an inherited pension depends on several factors, including the type of pension benefit, the age of the pension holder at death and how the beneficiary accesses the money.
For deaths before age 75, certain inherited pension benefits can currently be paid without Income Tax where the relevant conditions are satisfied.
When the pension holder dies aged 75 or older, withdrawals by an individual beneficiary will generally be taxable at the beneficiary’s marginal Income Tax rate.
There are additional rules involving the Lump Sum and Death Benefit Allowance and the timing of certain lump-sum death benefits.
A major additional change is approaching from 6 April 2027.
Finance Act 2026 has legislated for most unused pension funds and pension death benefits to be brought within the deceased person’s estate for Inheritance Tax purposes for deaths occurring on or after that date.
The government has confirmed that the change will apply from 6 April 2027, even where pension benefits are paid to beneficiaries later.
If the pension member dies before 6 April 2027, the existing rules continue to apply to that death.
Death-in-service benefits payable from registered pension schemes are among the benefits excluded from the new IHT treatment.
This represents an important shift for estate planning because pensions have historically often been treated differently from many assets held directly in an estate.
Anyone relying on a pension as part of an inheritance strategy should therefore review that plan before the new regime takes effect.
Final Thoughts
Avoiding unnecessary pension tax is usually about planning when and how income is withdrawn, rather than trying to make all pension income tax-free.
For 2026/27, the most important figures to remember are the £12,570 standard Personal Allowance, the normal 25% tax-free pension entitlement, the standard £268,275 Lump Sum Allowance, the £60,000 Annual Allowance and the £10,000 Money Purchase Annual Allowance.
The full new State Pension is also now close to the standard Personal Allowance, meaning retirees receiving the full amount may have very little unused allowance available for private pension income.
Carefully coordinating State Pension, private pensions, workplace pensions, ISAs and other income can therefore make a substantial difference to the tax ultimately paid.
Large or irreversible pension decisions should be considered carefully, particularly where higher-rate tax, the MPAA, protected pension rights or inheritance planning are involved.
Frequently Asked Questions
How Much Pension Can I Take Without Paying Tax?
You can normally take up to 25% of your pension tax-free, subject to your available Lump Sum Allowance. Any taxable pension income may also fall within your Personal Allowance.
Can I Take 25% Of My Pension Tax-Free Every Year?
No. You cannot normally take 25% of your entire pension tax-free every year, although you may be able to phase tax-free cash as different parts of your pension are accessed.
Is The State Pension Taxable?
Yes. The State Pension counts as taxable income, although tax is not usually deducted directly from the payment before you receive it.
What Is The Most Tax-Efficient Way To Withdraw A Pension?
For many people, spreading taxable withdrawals across tax years and staying within lower tax bands can reduce the overall tax bill.
Can I Take Tax-Free Cash From More Than One Pension?
Yes, but the standard Lump Sum Allowance applies across your pensions rather than giving you a separate full allowance for each pension.
Do I Pay National Insurance On Pension Income?
No. Pension income is generally not subject to National Insurance, although Income Tax may still be payable.
Can I Cash In A Small Pension Without Paying Tax?
Not always. A qualifying pension pot of £10,000 or less can often be taken as a small-pot lump sum, but normally only 25% is tax-free and the remainder is taxable.
What is your reaction?