Moving Money To The UK: Tax Rules You Need To Know In 2026

Last Updated: 26.10.2026
Transferring money from another country into a UK bank account does not automatically mean that HM Revenue & Customs will charge tax on the amount received.
The tax position normally depends on where the money came from, what it represents, when the income or gain arose and whether the recipient is UK tax resident.
A transfer of existing savings can therefore have a very different tax outcome from bringing foreign salary, rental income, investment gains or proceeds from selling overseas property into Britain.
The rules changed significantly from 6 April 2025 when the old remittance basis was abolished and replaced by the Foreign Income and Gains regime for qualifying new UK residents. Those changes remain particularly important during the 2026/27 tax year.
When Does An Overseas Money Transfer Create A UK Tax Bill?
The transfer itself is generally not the event that determines whether Income Tax or Capital Gains Tax is payable.
Instead, HMRC looks at the underlying source of the money.
For example, transferring £50,000 that has been held as existing savings may have a very different tax treatment from receiving £50,000 of foreign employment income during a year in which you are UK resident.
A UK resident will normally be taxable on foreign income unless a specific exemption or relief applies.
Non-UK residents generally do not pay UK tax on foreign income, although separate rules can apply to UK-source income and certain UK assets.
This means taxpayers should establish three points before moving a large amount into Britain:
- Identify The Source Of The Money: Determine whether it represents savings, income, a gain, a gift or inheritance
- Check Your UK Residence Status: Tax residence can determine whether foreign income and gains fall within UK taxation
- Check Available Reliefs: FIG relief, foreign tax credits and treaty provisions can materially change the final liability
Simply sending money from one bank account to another does not turn existing capital into taxable income.
What Types Of Overseas Money Can Be Taxable In The UK?
Different sources of money can receive different UK tax treatment.
| Type Of Overseas Money | Main UK Tax Consideration |
| Existing Savings | Usually depends on how and when the savings were originally generated |
| Foreign Salary | Income Tax may apply |
| Overseas Business Income | Income Tax may apply |
| Foreign Bank Interest | Income Tax may apply |
| Foreign Dividends | Income Tax may apply |
| Overseas Rental Income | Income Tax may apply |
| Foreign Pension Income | Income Tax may apply depending on the circumstances |
| Investment Sale Proceeds | Capital Gains Tax may apply to the gain |
| Foreign Property Sale | Capital Gains Tax may apply to the gain |
| Gifts | Normally not Income Tax merely because the recipient receives a genuine gift |
| Inheritance | Inheritance Tax and residence rules may need consideration |
HMRC specifically lists foreign wages, investment income, overseas property rental income and foreign pensions among the types of foreign income that may need to be taxed in the UK.
It is therefore important not to assume that the entire value entering the account is taxable.
When property or investments are sold, for example, tax is generally concerned with the taxable gain, rather than treating the whole sale price as income.
How Does UK Tax Residence Affect Money Transferred From Overseas?
UK tax residence is one of the most important factors when assessing foreign money.
The Statutory Residence Test considers factors including days spent in Britain, homes, employment and personal ties.
Someone may automatically be UK resident where, among other tests, they spend at least 183 days in the UK during the tax year. Other automatic UK and overseas tests can also determine residence.
Broadly:
- UK Residents: Normally pay UK tax on worldwide income and gains unless a relief applies
- Non-UK Residents: Generally do not pay UK tax on foreign income
- People Moving During The Tax Year: Split-year treatment can sometimes divide a tax year between UK-resident and non-resident periods
Residence should therefore be established before deciding whether overseas income needs to be reported.
How Does The 4-Year Foreign Income And Gains Regime Work?
One of the biggest changes affecting international transfers is the Foreign Income and Gains regime, commonly called the FIG regime.
The regime started on 6 April 2025 and replaced the previous remittance-basis system.
A qualifying new resident can claim relief on eligible foreign income and gains arising during their first four years of UK residence where they previously spent at least 10 consecutive tax years as a non-UK resident.
Eligible sources can include:
- Foreign Bank Interest
- Foreign Dividends
- Overseas Property Business Profits
- Profits From A Trade Carried On Wholly Outside The UK
- Qualifying Foreign Capital Gains
Foreign employment income is dealt with differently and may instead qualify for Overseas Workday Relief where the relevant requirements are met.
Who Can Claim FIG Relief?
The regime is not available simply because someone holds foreign money.
The individual generally needs to be within their first four tax years of UK residence following at least 10 consecutive tax years of non-UK residence.
The four-year period begins when UK residence begins. Unused qualifying years cannot simply be carried forward indefinitely.
Can Foreign Income And Gains Be Brought To The UK Tax-Free?
Where qualifying foreign income or gains receive FIG relief, HMRC permits those amounts to be brought to the UK without an additional tax charge simply because they are remitted.
This is a major difference from the previous remittance-basis system.
Claiming FIG relief can, however, mean losing certain allowances, including the Income Tax Personal Allowance and Capital Gains Tax annual exempt amount for the relevant year.
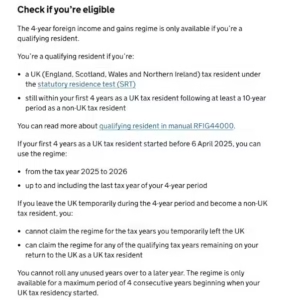
HMRC confirms the eligibility rules and foreign income and gains that can qualify under the four-year FIG regime.
What Is The Temporary Repatriation Facility?
The Temporary Repatriation Facility, or TRF, is aimed mainly at people who previously used the old remittance basis.
Some former remittance-basis users still hold foreign income and gains that arose before 6 April 2025 outside the UK. Bringing those amounts into Britain without appropriate planning could otherwise create tax consequences.
The TRF runs for three tax years:
| Tax Year | TRF Rate |
| 2025/26 | 12% |
| 2026/27 | 12% |
| 2027/28 | 15% |
Eligible former remittance-basis users can designate qualifying overseas amounts and pay the special TRF rate. For the current 2026/27 tax year, the rate remains 12%.
Using the facility requires an election through the appropriate Self Assessment pages.
The rules can become particularly complicated where mixed offshore accounts, trusts or historic foreign income and gains are involved.
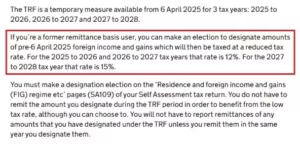
HMRC confirms that the Temporary Repatriation Facility applies for three tax years with a 12% rate in 2026/27 and 15% in 2027/28.
Do You Pay Tax On Gifts And Inheritances Received From Overseas?
Receiving a genuine cash gift from another person does not normally turn that money into taxable employment or investment income simply because it reaches a UK bank account.
However, gifts can interact with Inheritance Tax.
UK rules provide a £3,000 annual gift exemption for a donor, along with other exemptions in particular circumstances. Gifts that are not otherwise exempt can potentially fall outside Inheritance Tax where the donor survives for seven years after making them.
The rules around declaring cash gifts to HMRC are therefore different from simply applying an Income Tax percentage to every gift received.
The recipient should nevertheless retain evidence showing that the payment was genuinely a gift, particularly where a large sum is transferred internationally.
Inheritance is also more complicated than simply asking whether money arriving in a UK account is taxable.
Since 6 April 2025, the previous domicile-based approach to Inheritance Tax has been replaced by long-term UK residence rules.
A person can generally become a long-term UK resident after being UK resident for 10 consecutive years or for at least 10 of the previous 20 tax years. Overseas assets may then fall within the UK IHT regime.
Families dealing with larger estates should therefore consider the overall estate position, available nil-rate bands and residence history.
The treatment of allowances can also become important when calculating Inheritance Tax after the death of a second parent.
Do You Pay Tax When Transferring Money From Overseas Property Or Investments?
Selling a property or investment abroad and transferring the proceeds to Britain does not normally mean the entire amount transferred becomes taxable.
The relevant issue is generally whether a taxable capital gain arose when the asset was sold.
For most UK residents, foreign gains fall within the UK Capital Gains Tax system.
For an overseas property, a simplified starting calculation is:
Sale Price − Acquisition Cost − Allowable Costs = Capital Gain
Further adjustments can then apply for capital losses, reliefs and exemptions.
Exchange rates can also affect the UK calculation because acquisition and disposal figures may need to be converted into sterling at the appropriate points.
Anyone selling a house or investment property outside Britain should therefore consider the UK rules on Capital Gains Tax on foreign property before assuming that moving the sale proceeds is tax-free.
Qualifying new residents should separately check whether the foreign gain could receive relief under the four-year FIG regime.
What Happens If You Have Already Paid Tax Overseas?
Being taxed abroad does not necessarily mean that the same income must be taxed twice without relief.
The UK has double-taxation arrangements with numerous countries, and Foreign Tax Credit Relief can potentially reduce the UK liability where tax has already been charged overseas.
HMRC instructs taxpayers to include income already taxed abroad when completing the foreign section of Self Assessment where they want to claim eligible Foreign Tax Credit Relief.
The amount of relief available depends on the circumstances and applicable treaty.
Foreign tax paid should therefore not simply be ignored when calculating UK liability.
Keep evidence including:
- Foreign Tax Assessments
- Tax Payment Receipts
- Foreign Payslips
- Dividend Statements
- Rental Statements
- Property Sale Tax Documents
The relief does not necessarily produce a refund where the overseas tax exceeds the equivalent UK charge.
Is There A Maximum Amount You Can Transfer To The UK Without Tax?
There is no single universal amount of money that every person can transfer into a UK bank account before UK tax automatically becomes payable.
A person could potentially transfer a large amount of legitimate existing capital without creating a new Income Tax charge from the transfer itself.
Conversely, a smaller amount could represent taxable foreign income.
The source and tax history of the money matter more than the transfer value alone.
Is The £10,000 Reporting Rule Applicable To Bank Transfers?
The frequently quoted £10,000 threshold is often misunderstood.
The £10,000 declaration requirement applies to physical cash being carried into or out of Great Britain when travelling to or from another country. GOV.UK states that cash equivalent to £10,000 or more must be declared in those circumstances.
It should not be interpreted as a general rule saying that every electronic international bank transfer above £10,000 must personally be reported to HMRC simply because of its size.
Banks can nevertheless carry out their own compliance and anti-money-laundering checks on large or unusual transactions.
What Documents Can UK Banks Request For Large Overseas Transfers?
A bank may ask questions about where a large payment came from, particularly where the transaction differs substantially from normal activity on the account.
Source-of-funds checks are designed to establish both where the money was transferred from and how the customer originally acquired it.
HMRC’s anti-money-laundering guidance explains that simply showing the sending bank account may not be enough. Evidence may also be required to demonstrate how the funds were generated.
Common documents can include:
- Bank Statements: Showing how savings accumulated and where the funds were held
- Payslips: Supporting money accumulated from employment
- Employment Records: Confirming salary, bonuses or other earnings
- Property Sale Documents: Showing the property sold and completion amount
- Investment Statements: Supporting proceeds from shares, funds or other investments
- Probate Documents: Showing that money originated from an inheritance
- Gift Letters: Confirming the identity of the donor and nature of the payment
- Business Accounts: Supporting profits or proceeds generated by a company or business
- Tax Records: Showing that relevant income or gains were properly declared
Business owners receiving international commercial payments should also keep business and personal transactions clearly documented rather than relying only on activity passing through a UK business bank account.
A bank asking for these documents does not itself mean tax is due. Banking compliance and tax liability are separate issues.
How Do You Report Foreign Income And Gains To HMRC?
UK residents who have taxable foreign income or capital gains will usually need to report them through Self Assessment.
The foreign pages of the return are used to record relevant overseas income and gains. FIG relief claims are also made through Self Assessment.
For income arising during 2025/26, the current online Self Assessment filing and payment deadline is 31 January 2027. HMRC’s October 2026 reminder confirms that taxpayers still completing their 2025/26 return have until that date to submit online and pay tax due.
Foreign income arising in the current 2026/27 tax year will normally form part of the return filed after the tax year ends on 5 April 2027.
Taxpayers who are newly required to complete Self Assessment generally need to notify HMRC by 5 October following the relevant tax year.
Record keeping is especially important for international income.
Keep evidence of:
- Original Foreign Income
- Dates Income Arose
- Foreign Tax Paid
- Relevant Exchange Rates
- Purchase And Sale Prices
- Bank Transfer Records
- FIG Or TRF Calculations
- Source-Of-Funds Documents
From April 2026, Making Tax Digital for Income Tax also began applying to the first group of qualifying sole traders and landlords.
People within that regime have additional digital record-keeping and quarterly update responsibilities, making the wider HMRC Making Tax Digital changes relevant where overseas property or business income forms part of their taxable activities.
Tax Implications Of Transferring Money From The US And India To The UK
The basic UK principle is similar regardless of whether money arrives from America, India or another country.
The UK tax consequences depend primarily on the person’s residence status and the source of the money rather than the country from which the bank transfer was sent.
For transfers from the United States, the UK and US have a double-taxation convention dealing with income and capital gains.
US citizens can face additional complexity because the US generally continues to tax citizens on worldwide income even when they live abroad. Treaty rules and foreign tax credits can therefore be particularly important.
For transfers from India, the UK and India also have a double-taxation convention covering income and capital gains.
Indian residents sending money overseas may separately need to consider India’s Liberalised Remittance Scheme.
The RBI scheme generally permits resident individuals to remit up to US$250,000 per financial year for permitted transactions, while India’s TCS threshold for relevant LRS remittances was increased from ₹7 lakh to ₹10 lakh.
Those Indian rules determine obligations at the sending end. They do not replace the separate UK analysis of whether the underlying money represents taxable income, gains, savings, gifts or another category.
Final Thoughts
The main tax question when transferring money to the UK is not simply how much is being transferred. It is what the money represents and when any income or gain arose.
The abolition of the remittance basis and introduction of the four-year FIG regime have significantly changed the rules for internationally mobile individuals.
Former remittance-basis users also have a limited opportunity to use the Temporary Repatriation Facility, including the 12% rate applying during 2026/27.
Anyone transferring substantial foreign income, historic offshore funds, overseas property proceeds or mixed-source accounts should establish the tax treatment before moving the money.
Keeping clear records of the source of funds, foreign tax already paid and relevant dates can make both HMRC reporting and bank compliance significantly easier.
For large or complex transfers, professional UK tax advice may be appropriate, particularly where more than one country’s tax system is involved.
FAQs About Tax Implications Of Transferring Money To The UK
Do I Have To Pay Tax On Money Transferred From Overseas To The UK?
Not simply because money was transferred. The tax treatment depends on what the money represents, your UK tax residence and whether the underlying foreign income or gain is taxable in Britain.
How Much Money Can I Transfer To The UK Tax-Free?
There is no general UK bank-transfer threshold that determines whether tax is payable.
A large transfer of existing capital may have no new Income Tax liability, while a smaller amount of taxable foreign income could need to be reported.
Is Money Transferred Between My Own Bank Accounts Taxable?
Moving your own existing money between accounts does not normally create income simply because the transfer takes place. However, tax may already be due on the income or gains from which that money originated.
Will HMRC Know If I Receive Money From Abroad?
Banks and financial institutions have extensive reporting and anti-money-laundering obligations.
Taxpayers should therefore keep accurate records and declare foreign income and gains where required rather than assuming an overseas transfer is invisible.
Do I Have To Declare A Large International Bank Transfer?
There is no universal rule requiring an individual to report every electronic transfer merely because it exceeds £10,000.
However, taxable foreign income and gains must be reported where required, and a bank may request evidence explaining the source of large transfers.
Do I Pay UK Tax On Savings Earned Before Moving To The UK?
Simply transferring existing savings is not normally the same as earning new income.
However, the history of those funds matters, especially where the account includes foreign income or gains arising while the individual was UK resident.
Is Gift Money From Overseas Taxable In The UK?
A genuine cash gift is not normally Income Tax for the recipient simply because it is received from abroad. Inheritance Tax rules, donor residence and the seven-year rule may still need consideration.
Do I Pay Tax On Money Inherited From Abroad?
Receiving an overseas inheritance does not automatically create Income Tax on the entire amount.
Inheritance Tax and long-term residence rules can still apply depending on the deceased person’s circumstances, estate and location of assets.
Can I Transfer Foreign Income To The UK Under The FIG Regime?
Yes, where eligible foreign income or gains have received FIG relief, qualifying amounts can generally be brought into the UK without an additional tax charge merely because they are remitted. FIG eligibility must first be established.
Can My Bank Ask Where An Overseas Transfer Came From?
Yes. Banks may request evidence of the source of funds, particularly for large or unusual payments.
Documents such as bank statements, property sale records, payslips, investment statements, probate documents or gift letters can help establish where the money originated.
What is your reaction?