What Is The Inheritance Tax Threshold And How Much Can You Inherit Tax-Free In The UK?

Last Updated: 3 November 2026
The Inheritance Tax threshold in the UK is £325,000 for the 2026/27 tax year. This is known as the nil-rate band.
If the value of an estate is below this amount, there is normally no Inheritance Tax (IHT) to pay.
If a person leaves a qualifying home to their children, grandchildren or certain other direct descendants, the £175,000 residence nil-rate band may also be available.
This can potentially increase an individual’s total tax-free threshold to £500,000.
For married couples and civil partners, unused allowances can sometimes transfer to the surviving partner.
Where both the standard nil-rate bands and residence nil-rate bands are fully available, the combined threshold can potentially reach £1 million on the second death. It is not an automatic £1 million exemption for every couple.
Inheritance Tax is primarily a tax on the deceased person’s estate, including property, money and possessions.
The standard rate is 40%, but it normally applies only to the taxable part of the estate above the available allowances and after relevant exemptions and reliefs have been considered.
Beneficiaries do not normally pay the IHT directly because it is generally dealt with by the executor or personal representative from estate funds.
Inheritance Tax Thresholds For 2026/27 At A Glance
The amount that can pass without IHT depends on the person’s circumstances rather than there being one threshold for every estate.
| IHT Allowance Or Rate | 2026/27 Amount |
| Standard Nil-Rate Band | £325,000 |
| Residence Nil-Rate Band | Up To £175,000 |
| Potential Individual Threshold With RNRB | Up To £500,000 |
| Potential Combined Basic Threshold For Married Couples/Civil Partners | Up To £650,000 |
| Potential Combined Threshold Including RNRB | Up To £1 Million |
| RNRB Taper Starts | £2 Million Estate Value |
| Standard IHT Rate | 40% |
| Reduced Charity Rate | 36% |
The £325,000 basic nil-rate band has remained unchanged since 6 April 2009. The residence nil-rate band is currently £175,000, subject to its qualifying conditions.
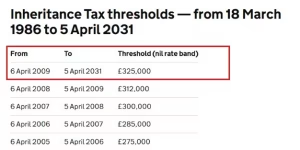
Official HMRC threshold table confirming the £325,000 Inheritance Tax nil-rate band and current residence nil-rate band.
How Is Inheritance Tax Calculated Above The Threshold?
Inheritance Tax is not normally charged at 40% on the entire estate.
Instead, the applicable allowances, exemptions and reliefs are deducted first and the standard 40% rate is then applied to the remaining taxable value.
A simplified calculation is:
Estate Value − Available Tax-Free Allowances = Taxable Estate
Taxable Estate × 40% = Potential Inheritance Tax
The actual calculation can be more complicated where lifetime gifts, trusts, business assets, agricultural assets, overseas property or transferred allowances are involved.
Example of Inheritance Tax On A £500,000 Estate
Suppose a single person dies with an estate worth £500,000 and does not qualify for the residence nil-rate band.
- Estate Value: £500,000
- Nil-Rate Band: £325,000
- Taxable Amount: £175,000
- Standard IHT Rate: 40%
- Potential IHT Bill: £70,000
This matches the basic calculation used by GOV.UK to illustrate how IHT is charged above the standard threshold.
Example Using The Residence Nil Rate Band
Now assume the same £500,000 estate includes a qualifying home that is left to a direct descendant and the full £175,000 residence nil-rate band is available.
The estate could potentially have:
£325,000 Standard Nil-Rate Band + £175,000 Residence Nil-Rate Band = £500,000
In that situation, there could be no IHT to pay on a £500,000 estate, provided all the qualifying conditions are satisfied.
Why Can The Inheritance Tax Threshold Be £325,000, £500,000, £650,000 Or £1 Million?
Different IHT figures are often quoted because they relate to different combinations of allowances.
£325,000 is the standard nil-rate band available to an individual.
£500,000 may be available to one person when the full £325,000 nil-rate band and £175,000 residence nil-rate band apply.
£650,000 can potentially be available on the death of a surviving spouse or civil partner where the deceased partner’s entire unused basic nil-rate band is transferred.
£1 million can potentially apply where a qualifying surviving spouse or civil partner has both partners’ £325,000 nil-rate bands and both £175,000 residence nil-rate bands available.
This is why the circumstances surrounding an estate matter. For example, the calculation of Inheritance Tax when the second parent dies can depend heavily on how much of the first parent’s allowances were used and whether a qualifying home passes to direct descendants.
Inheritance Tax Threshold For Married Couples And Civil Partners
Transfers between spouses and civil partners are generally exempt from Inheritance Tax, subject to the relevant conditions.
An important additional benefit is that an unused percentage of the first spouse or civil partner’s basic nil-rate band can potentially transfer to the survivor’s estate.
If none of the first person’s £325,000 nil-rate band was used, the surviving spouse or civil partner could potentially have:
£325,000 + £325,000 = £650,000
of basic nil-rate band available when they die.
HMRC transfers the unused percentage, rather than simply transferring a fixed cash amount.
A claim is normally made by the personal representatives dealing with the surviving partner’s estate.
If both partners’ full residence nil-rate bands are also available, another £350,000 may potentially be added:
£650,000 Basic Nil-Rate Bands + £350,000 Residence Nil-Rate Bands = £1 Million
Again, this £1 million figure is a potential maximum under qualifying circumstances, not an automatic allowance for every married couple.
When Does The £175,000 Residence Nil Rate Band Apply?
The residence nil-rate band, or RNRB, is an additional IHT allowance that can apply when a person leaves a qualifying home to their direct descendants.
For 2026/27, the maximum RNRB is £175,000.
The amount actually available is generally limited by factors including:
- Property Value: The qualifying share of the home must be sufficient to use the allowance
- Beneficiary: The home must pass to qualifying direct descendants
- Estate Value: The allowance starts to taper when the estate exceeds £2 million
- Previous Use: Transferred RNRB from a deceased spouse or civil partner may affect the total available
The RNRB is deducted from the estate rather than simply making the home itself completely exempt from IHT.
Who Counts As A Direct Descendant?
For RNRB purposes, direct descendants can include:
- Children
- Grandchildren And Other Lineal Descendants
- Adopted Children
- Stepchildren
- Foster Children
- Certain Children For Whom The Deceased Was A Guardian
- Spouses Or Civil Partners Of Qualifying Lineal Descendants
Nephews, nieces and siblings are not normally treated as direct descendants for the residence nil-rate band.
What Happens To The Residence Nil Rate Band Above £2 Million?
The RNRB begins to reduce where the value of the estate exceeds £2 million.
For every £2 by which the estate exceeds £2 million, the available residence nil-rate band is reduced by £1.
For example, if an estate were £100,000 above the £2 million threshold, the RNRB could be reduced by £50,000.
Importantly, the value used for this taper calculation is determined before deducting certain exemptions and reliefs such as spouse exemption, Agricultural Relief and Business Relief.
Can You Claim The Residence Nil Rate Band After Downsizing?
Potentially, yes.
A person who downsized, sold or gave away a former home on or after 8 July 2015 may still qualify for a downsizing addition where the relevant requirements are met and other assets are ultimately left to direct descendants.
This prevents someone automatically losing the additional IHT allowance simply because they moved to a smaller property or disposed of their former home before death.
Which Gifts Are Exempt From Inheritance Tax?
Giving assets away during your lifetime can affect the eventual IHT calculation, but several gift exemptions are available.
The main allowances include:
- Annual Exemption: Up to £3,000 of gifts each tax year
- Unused Annual Exemption: Can normally be carried forward for one tax year
- Small Gifts: Up to £250 per person, subject to the rules
- Wedding Gift To A Child: Up to £5,000
- Wedding Gift To A Grandchild Or Great-Grandchild: Up to £2,500
- Wedding Gift To Another Person: Up to £1,000
- Normal Expenditure Out Of Income: Regular affordable gifts from normal income may qualify for exemption
The exemptions have their own conditions, so keeping clear records of significant gifts can be important when an estate is later administered.
HMRC treatment of cash gifts and whether they need to be declared also depends on factors including the nature of the gift and what happens during the following years.
What Is The 7-Year Rule For Inheritance Tax?
Many outright lifetime gifts to individuals can become exempt from IHT if the donor survives for seven years after making them.
If the donor dies within seven years, the gift may have to be considered when calculating IHT.
Taper relief can reduce the tax charged on certain gifts when the donor survives for more than three years after making the gift.
It should not be interpreted as simply reducing the value of every gift made during the seven-year period.
The order and total value of lifetime gifts can also affect how the nil-rate band is used, so large gifts may require a more detailed calculation.
How Do Business And Agricultural Assets Affect Inheritance Tax?
Business owners and farming families can have additional reliefs available, but significant changes took effect from 6 April 2026.
A new £2.5 million allowance applies to the combined value of qualifying property eligible for the 100% rate of Agricultural Property Relief or Business Property Relief.
Once the available £2.5 million allowance has been used, qualifying property above that level generally receives relief at 50% rather than 100%.
Unused allowance can also potentially transfer to a surviving spouse or civil partner, meaning up to £5 million of qualifying agricultural or business property could receive 100% relief between a couple where the full conditions are met.
Certain shares traded on markets that do not meet HMRC’s definition of listed receive Business Relief at 50% rather than using the £2.5 million 100% allowance.
These reliefs are separate from the standard £325,000 nil-rate band and should not be confused with the normal IHT threshold.
Does The Inheritance Tax Threshold Apply To Overseas Assets?
Whether overseas assets fall within UK Inheritance Tax depends partly on the deceased person’s UK residence history.
Since 6 April 2025, the previous domicile-based approach has been replaced for these purposes by a long-term UK residence test.
Broadly, an individual can be treated as a long-term UK resident where they have been UK resident for at least 10 of the previous 20 tax years.
Where the test applies, overseas assets may come within the UK IHT calculation.
Someone who is not within the long-term residence rules may generally have a more limited UK IHT exposure to UK assets, although trusts and individual circumstances can produce different outcomes.
Overseas property can also create taxes other than IHT. For example, selling an inherited or personally owned overseas home can raise separate questions about Capital Gains Tax on foreign property.
How Will Pension Changes From April 2027 Affect Inheritance Tax?
A major change takes effect for deaths occurring on or after 6 April 2027.
Most unused pension funds and pension death benefits will be brought within the value of the deceased person’s estate for Inheritance Tax purposes.
The reform was legislated through Finance Act 2026, so it is no longer simply a policy proposal.
HMRC is continuing to introduce the supporting administrative rules and guidance ahead of implementation.
This does not mean every pension will automatically face a 40% IHT charge.
Instead, relevant pension wealth will generally become part of the IHT calculation.
Available nil-rate bands, exemptions and other rules still need to be considered before determining whether tax is actually due.
Someone whose non-pension estate is below their available IHT threshold could therefore move above it once relevant unused pension wealth is included after April 2027.
The detailed impact on estates and beneficiaries is covered further in the changes to Pension IHT rules from April 2027.
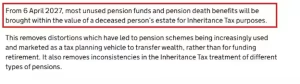
HMRC’s technical note confirms that most unused pension funds and pension death benefits will enter estates for IHT purposes from 6 April 2027.
Will The Inheritance Tax Threshold Increase?
The standard Inheritance Tax threshold is not currently scheduled to rise with inflation.
The £325,000 nil-rate band is fixed through the 2030/31 tax year. The residence nil-rate band and its £2 million taper threshold are also fixed at their current levels through 2030/31 under current government policy.
This matters because property, investments and other asset values can increase while the main IHT threshold remains unchanged.
The £325,000 threshold has already remained at the same level since 6 April 2009, meaning more estates can potentially move above it as asset values rise.
When Does Inheritance Tax Have To Be Paid?
Inheritance Tax generally needs to be paid by the end of the sixth month after the month in which the person died.
For example, where a person dies during January, the IHT payment deadline is normally 31 July.
Interest can be charged where tax remains unpaid after the deadline. In many cases, at least some IHT must also be paid before the personal representatives can obtain probate, known as confirmation in Scotland.
Certain assets that may take time to sell can qualify for payment by annual instalments over 10 years.
From 6 April 2026, qualifying Agricultural Relief and Business Relief assets can benefit from interest-free instalment treatment under the new rules, provided payments themselves are made on time.
How Can You Reduce An Inheritance Tax Liability Legally?
IHT planning depends on individual circumstances, but legitimate options can include using exemptions and reliefs that Parliament has specifically provided.
Possible considerations include:
- Using Gift Allowances: Make use of available annual and other gift exemptions
- Planning Early: Gifts made sufficiently far in advance may fall outside the estate under the seven-year rules
- Using Spouse Exemption: Qualifying transfers between spouses and civil partners can be exempt
- Using The Residence Nil Rate Band: A qualifying home left to direct descendants can increase the available threshold
- Keeping Gift Records: Maintain dates, values and details of significant lifetime transfers
- Reviewing Business Reliefs: Qualifying business or agricultural property may receive substantial IHT relief
- Considering Charitable Gifts: Qualifying charitable gifts can be exempt and may reduce the applicable rate on part of an estate to 36%
- Reviewing Pension Planning: The April 2027 rules may materially alter the value included in an estate
Estate planning should focus on using legitimate exemptions and reliefs rather than assuming that transferring ownership automatically removes an asset from IHT.
For example, giving away a home but continuing to live in it rent-free can result in separate “gift with reservation” considerations.
Professional tax or estate-planning advice may be particularly important for large estates, trusts, businesses, farms, overseas assets or substantial lifetime gifts.
Conclusion
The standard Inheritance Tax threshold is £325,000 in the UK for 2026/27, but that is only the starting point.
An individual could potentially have up to £500,000 available when the full residence nil-rate band applies.
A surviving spouse or civil partner may have up to £650,000 of basic nil-rate band after transferring unused allowance from their late partner, while qualifying couples may potentially reach the frequently quoted £1 million threshold when both residence nil-rate bands are also available.
However, eligibility depends on the estate, beneficiaries, property ownership, lifetime gifts and available reliefs.
The threshold is currently frozen through 2030/31, while recent Business Relief and Agricultural Relief changes and the introduction of IHT on most unused pension wealth from April 2027 mean estate planning should be based on current rules rather than older IHT figures.
Frequently Asked Questions
How Much Can You Inherit Without Paying Tax In The UK?
There is normally no IHT where the deceased’s estate is within its available tax-free allowances. The standard individual nil-rate band is £325,000, although additional allowances can increase this figure.
What Is The Inheritance Tax Threshold For A Single Person?
The standard threshold for a single person is £325,000. It can potentially rise to £500,000 where the full £175,000 residence nil-rate band applies.
What Is The Inheritance Tax Threshold For A Married Couple?
Each spouse or civil partner has their own £325,000 nil-rate band. If the first partner leaves it unused, the survivor’s estate can potentially have up to £650,000 of basic nil-rate band.
Can The Inheritance Tax Threshold Be £500,000?
Yes. An individual with the full £325,000 basic nil-rate band and the full £175,000 residence nil-rate band could potentially have a total threshold of £500,000.
How Can A Couple Have A £1 Million Inheritance Tax Threshold?
A qualifying surviving spouse or civil partner may potentially combine two £325,000 basic nil-rate bands and two £175,000 residence nil-rate bands. This can produce a maximum combined allowance of £1 million, subject to the relevant conditions.
Do Children Pay Inheritance Tax On Money They Inherit?
Beneficiaries do not normally pay IHT directly on assets they inherit because the tax is usually paid from the deceased’s estate. Separate taxes can arise later, such as Income Tax on investment income or Capital Gains Tax when an inherited asset is sold.
Does Giving Away A House Avoid Inheritance Tax?
Not automatically. A genuine lifetime gift may eventually fall outside the estate, but the seven-year rules and gift-with-reservation rules can still apply, particularly if the person continues to benefit from the property after giving it away.
What is your reaction?